AC Damaged by a Hurricane? How the Claim Actually Works
Document first, call the carrier second, and be careful what you sign in the week after a storm.
By Roman Shatokhin · Airo Service · September 2026
Do this before you do anything else
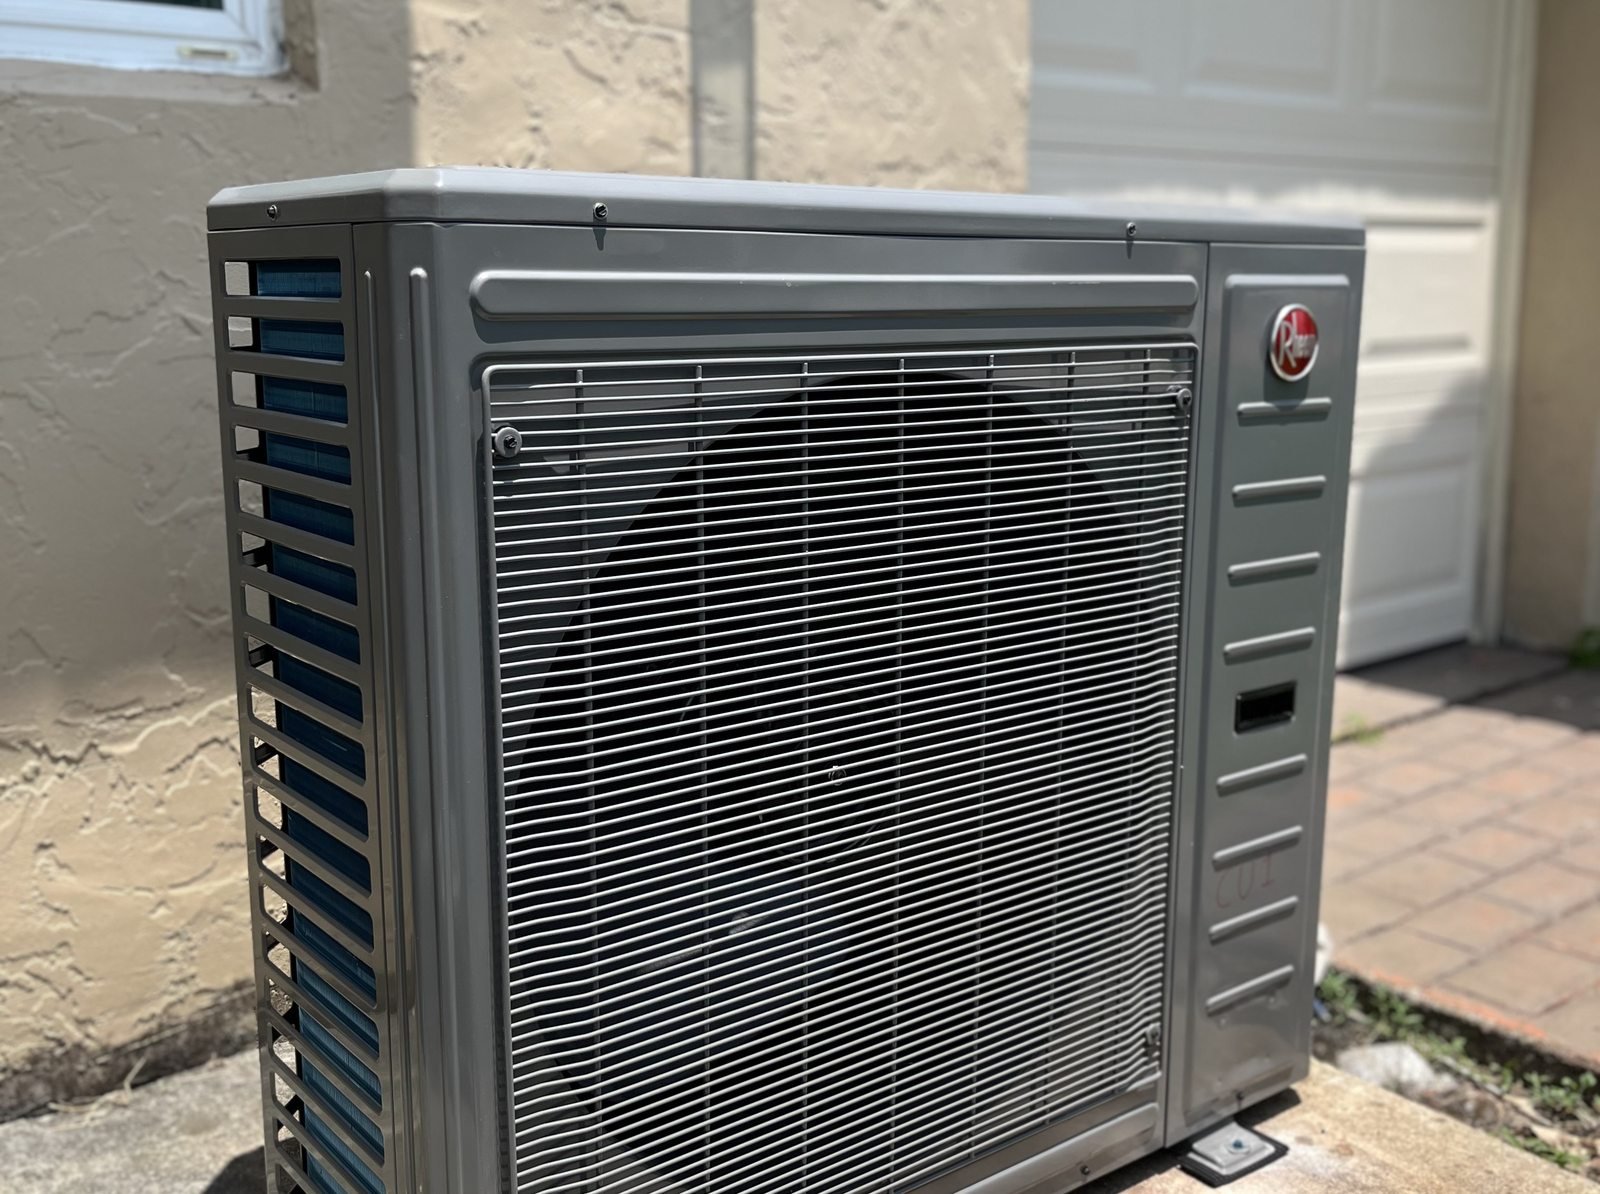
- Photograph everything, from several angles, before anything is moved, cleared or repaired. Include the equipment, the pad, the tie-downs, the surrounding debris, and the data plate with the model and serial numbers.
- Do not switch the system on if the outdoor unit has been submerged, struck, or moved off its pad. Running a flooded or damaged unit can convert repairable damage into a total loss, and can create an electrical hazard.
- Take reasonable steps to prevent further damage — covering an opening, shutting off power at the breaker. Policies require this, and keep the receipts for anything you spend doing it.
- Do not throw anything away until the adjuster has seen it, including damaged components.
Documentation before repair is the single thing that most affects how a claim goes.
What is usually covered — and what is not
Every policy differs and yours governs, but the general shape in Florida:
- Wind damage to the outdoor unit — debris strikes, the unit being displaced, cabinet or coil damage. Generally covered under a standard homeowners policy.
- Falling trees or debris. Generally covered.
- Lightning damage to boards, compressors and controls. Generally covered, though carriers often ask for evidence linking the failure to the strike.
- Flood or storm surge. Not covered by homeowners insurance. That requires separate flood coverage. This is the single most common and most painful surprise, because a condenser that sat in surge water is usually finished.
- Power surge from the utility. Sometimes covered, sometimes excluded, sometimes subject to a separate endorsement. Check yours.
- Wear, age, corrosion and lack of maintenance. Not covered. A carrier may argue that a fifteen-year-old salt-corroded unit failed from age rather than from the storm, which is one more reason to keep service records.
The hurricane deductible
Florida policies typically carry a separate hurricane deductible, expressed as a percentage of the dwelling coverage — commonly 2% or 5% — rather than the flat dollar amount that applies to everything else. On a home insured for $500,000, a 2% hurricane deductible is $10,000.
The practical consequence: an air conditioner on its own frequently costs less than the hurricane deductible, so an AC-only claim may recover nothing while still being recorded as a claim. It is worth doing the arithmetic before filing. Where the AC is part of broader storm damage to the home, it belongs in that single claim rather than a separate one.
Deadlines
Florida tightened claim deadlines in recent years. Under current law, notice of a new or reopened property claim generally must be given to the carrier within one year of the date of loss, with a longer window for supplemental claims. Do not rely on this article for your specific situation — deadlines have changed more than once and your policy may be stricter. Report promptly, in writing, and confirm receipt.
The claim, step by step
- Report it to your carrier promptly, in writing where possible, and keep the claim number.
- Get a licensed contractor’s written assessment. A report from a licensed HVAC contractor stating what failed, why, and what repair or replacement requires carries considerably more weight than a homeowner’s description.
- Meet the adjuster on site if you can, and have your photographs and documentation ready.
- Keep a log of every call, name and date. Claims involve many people and short memories.
- Review the estimate carefully before accepting. Check that it includes permit, disposal, electrical, tie-downs and code-required items — the same list as in hidden costs of installation. Adjuster estimates commonly omit code upgrades.
- If you disagree, you can supply a competing contractor estimate, and many policies contain an appraisal clause for resolving disputes over amount.
Post-storm caution
The week after a hurricane brings out-of-area operators, door-knockers and pressure. Protect yourself:
- Verify the licence at myfloridalicense.com before anyone touches your equipment. It takes two minutes — see how to choose a contractor.
- Be very careful with anything you are asked to sign at the door, particularly documents that assign your insurance benefits to a contractor. Florida law has substantially restricted assignment of benefits for property claims in recent years, but paperwork still circulates. Do not sign anything you have not read, and never sign a blank or open-ended document.
- Avoid large cash deposits and anyone requiring payment before work.
- Get everything in writing, including what is and is not included.
- Be wary of a promise to “cover your deductible.” That is not a favour; in Florida it is a serious problem for both parties.
Preventing the next one
Some of this is genuinely preventable. Properly rated hurricane tie-downs keep a unit on its pad. A surge protector on the system reduces lightning and utility-surge losses. Clearing loose items from around the condenser removes projectiles. And elevating equipment where flooding is a known risk is worth discussing before the next season rather than after it.
The full seasonal routine is in the hurricane season AC prep checklist, and if you leave the property for part of the year, settings for an empty house covers what to do before you go.
This article is general information, not legal or insurance advice. Your policy language and current Florida law govern your claim — confirm specifics with your carrier or a licensed public adjuster or attorney.
Frequently Asked Questions
Does homeowners insurance cover AC damage from a hurricane?
Wind damage, debris strikes and lightning damage to an air conditioner are generally covered by a standard Florida homeowners policy. Flood and storm surge damage is not — that requires separate flood coverage, which is the most common and costly surprise after a storm.
Why might my AC claim recover nothing?
Because Florida policies usually carry a separate hurricane deductible set as a percentage of dwelling coverage, commonly 2 to 5 percent. On a home insured for $500,000 that is $10,000 to $25,000, and a replacement air conditioner alone often costs less than the deductible.
How long do I have to file a hurricane claim in Florida?
Under current Florida law, notice of a new or reopened property claim generally must be given within one year of the date of loss, with a longer window for supplemental claims. Deadlines have changed more than once, so report promptly in writing and confirm the specifics with your carrier.
Should I turn my AC on after a storm to test it?
Not if the outdoor unit was submerged, struck by debris or moved off its pad. Running a flooded or damaged unit can turn repairable damage into a total loss and can present an electrical hazard. Photograph it first, then have it assessed.
What should I be careful about after a hurricane?
Verify any contractor's licence at myfloridalicense.com before work begins, avoid large cash deposits, get everything in writing, and read anything you are asked to sign at the door — particularly documents assigning your insurance benefits. An offer to cover your deductible should be treated as a serious warning sign.
Storm Damage? Get It Documented Properly
Licensed assessment with written findings and photographs for your claim. Licensed and insured, $1M/$2M liability, COI on request.
- ✔ Free, No-Obligation Estimate
- ✔ Upfront Written Pricing — No Surprises
- ✔ 10-Yr Parts / 1-Yr Labor Warranty
- ✔ Serving Miami-Dade, Broward & Palm Beach
Prefer to talk? Call (305) 846-0155.